Cash Advance – Quick Borrow

Screenshots
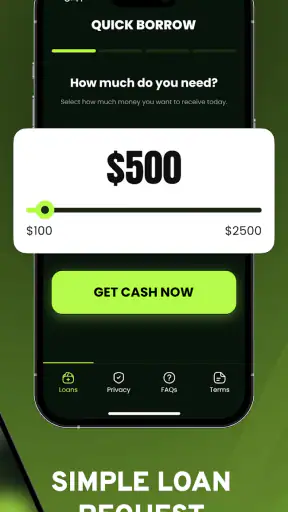
Details
- Rating
- 27.00 reviews
- Version
- 1.0.7
- Developer
- TIMECORE Studio
Analysis by Norviv
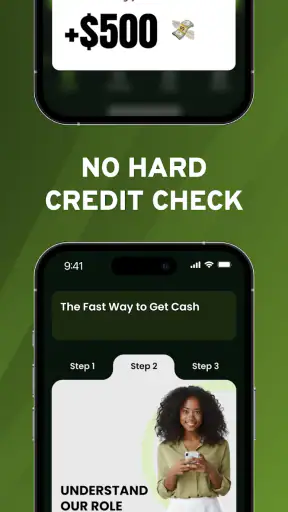
When an unexpected bill lands between paydays, the hardest part is often not deciding whether you need money, but finding a way to explore your options without spending an entire afternoon calling lenders. Cash Advance – Quick Borrow takes a focused approach to that problem: it lets me make an online request and look through available cash advance and personal loan offers from my phone. That single capability shapes the whole experience, and it is also the point where I think users need to be most careful.
I reviewed this finance app as a tool for comparing borrowing possibilities, not as a promise of guaranteed cash. The distinction matters. An app that helps you request offers can save time, but the offer itself, its repayment terms, and its total cost are what determine whether borrowing is sensible. Used with that mindset, it can be a practical first step for someone dealing with a short-term cash gap.
Cash Advance – Quick Borrow is free to install, aimed at everyone, and published by TIMECORE Studio. It has an average rating of 4.8 from around 942 ratings, with over 10K installs. The app was released on February 27, 2026, and version 1.0.7 requires Android 7.0 or later. Those details make it accessible to people using older Android phones, while the relatively recent release means I would still keep the app updated before submitting any financial request.
Requesting offers is the app’s central strength
The main value here is convenience. Instead of treating a cash advance or personal loan search as a series of separate applications, I can begin from one mobile workflow and see what possibilities are available to me. That is useful when speed matters, especially if I am trying to understand whether a borrowing option exists before committing time to a longer application.
The app’s store summary presents it as a way to get cash advance and personal loan offers through a fast online request. In practical terms, I see that as an offer-finding service rather than an automatic approval button. A request may lead to choices, but it does not turn a financial emergency into free money. The app is most useful when I want to organize the search, not when I expect certainty.
That distinction also changes how I read the interface. I would not judge the experience only by how quickly a form opens or how few screens it uses. The important question is whether I can slow down at the point where an offer appears, check the repayment obligation, and decide without feeling pushed. For a finance app, a calm review step is more valuable than a flashy promise of speed.
One practical advantage is that the request can be made online from a phone. If I am away from home, dealing with an urgent expense, or simply unable to visit a branch, that flexibility is meaningful. It also makes the app easier to try alongside other options, such as contacting my bank or reviewing a credit-union product.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
What the request process means in real life
I would approach the request as an information-gathering exercise. Before opening the app, I would decide the smallest amount that actually solves the problem and write down the date when I expect to repay it. That preparation prevents the convenience of a quick form from encouraging me to ask for more than I need.
After entering the requested information, I would expect to review any available offer carefully rather than accepting the first result. The useful comparison is not simply the amount offered. I would look at the total repayment, the timing of payments, any stated fees, and whether the schedule fits my regular income. If those details are difficult to understand, that is a reason to pause, not a reason to tap through faster.
A less obvious benefit of this approach is that it separates the emotional urgency of the situation from the decision itself. When a car repair or utility bill is pressing, I can easily focus only on receiving money. Using the app to gather an offer first gives me a short checkpoint: I can compare the obligation with the original bill and ask whether the new payment creates a second problem.
Another useful habit is to save the information I see in a private note before leaving the app. I would record the amount, repayment dates, and total cost in plain language, then compare it with my budget. This is not an extra feature claim about the app; it is a simple workflow that makes a fast mobile request safer and easier to evaluate later.
A realistic emergency example
Imagine I need to cover an urgent household repair before my next paycheck. I could use Cash Advance – Quick Borrow to request available options from my phone, then compare the borrowing cost with the repair bill. If the repayment would leave too little for rent, food, or transport, I would treat that as a clear warning even if the request itself was quick.
If the offer fits my budget, I would still check the schedule against my actual payday rather than assuming the timing works. A payment that arrives before income can turn a manageable loan into an overdraft or another borrowing cycle. The app can help me find an option, but only my budget can tell me whether that option is affordable.
This is where the service can be more useful than searching randomly online. I have a defined purpose, a defined amount, and a defined repayment plan. The request becomes a way to gather relevant possibilities instead of an invitation to borrow simply because an offer is visible.
Where it fits among familiar alternatives
The usual alternatives each have a different advantage. A bank may offer a relationship-based product with terms I already understand, while a credit union can be worth considering when I want personal guidance or a product designed around longer-term affordability. A direct lender’s own app may provide a more focused application experience, but it may also show fewer alternatives.
Cash Advance – Quick Borrow sits closer to the comparison stage. Its appeal is the ability to begin with an online request for cash advance and personal loan offers rather than immediately choosing one familiar provider. That can be helpful when I do not know which route is appropriate. On the other hand, a comparison-style starting point means I must do more of the judgment myself.
For a small, urgent need, the app may be more convenient than arranging an appointment. For a larger amount or a repayment period that extends well beyond the immediate emergency, I would lean toward speaking with a bank, credit union, or qualified financial adviser. A quick request is not automatically the best tool for a complicated borrowing decision.
The tradeoff between speed and careful reading
The strongest selling point is also the main risk: speed can make borrowing feel simpler than it really is. A fast online request reduces friction, but financial obligations should not be evaluated at the same speed as a food delivery order. I would use the app quickly to gather information, then deliberately slow down before agreeing to anything.
I also would not assume that a displayed offer is guaranteed, final, or suitable for every applicant. The app’s role is to connect the request with possible offers; approval and terms can depend on the individual situation. Anyone opening it should be prepared to provide accurate information and read the resulting conditions in full.
Privacy deserves attention as well. Because this is a finance app, I would avoid using it on a shared device and would review every screen before submitting personal details. I would also confirm that I am dealing with the intended service inside the official app marketplace, rather than installing an imitation with a similar name. These habits are especially important when an app handles information connected to borrowing.
There is also a psychological tradeoff. Seeing a possible amount can make that amount feel available before I have worked out the repayment. My own rule would be to decide my budget first and treat any offer above that limit as irrelevant. That small boundary keeps the app in its proper role as a search tool.
Another limitation is that a mobile request cannot replace personal advice when the underlying problem is recurring. If I need an advance every month to cover ordinary expenses, the right answer is probably a broader budget review, debt counseling, or a conversation with my bank. Repeating short-term borrowing can hide an income or spending issue instead of solving it.
Who benefits most from this app
I think the best match is someone who has a specific, short-term cash need and wants to explore offers without starting from several separate websites. That person should be comfortable comparing repayment details, checking a budget, and walking away when the cost is too high. The app’s free availability makes it easy to begin the search without paying an upfront app charge.
It may also suit someone who has limited time or uses an older Android phone. Support for Android 7.0 or later keeps the technical barrier relatively low, and the mobile format is convenient for people who cannot easily visit a branch during business hours. Still, technical accessibility should not be confused with financial suitability.
I would recommend skipping it if I already know the exact bank or credit-union product I want, because going directly to that provider may give me a clearer relationship and fewer steps. I would also skip it if I am looking for investment tools, expense tracking, bill reminders, or a complete personal-finance dashboard. This app is centered on borrowing requests, not everyday money management.
Someone with unstable income should be especially cautious. Even a modest repayment can become difficult when the next paycheck is uncertain. In that situation, I would first explore non-borrowing alternatives, such as negotiating a bill date, asking the service provider about a payment arrangement, or seeking trusted local assistance. The app can show a possible route, but it cannot remove the consequences of repayment.
How I would use it responsibly
My process would be simple but strict. First, I would define the emergency and the minimum amount needed. Second, I would submit only accurate information. Third, I would compare the offer’s complete repayment obligation with my income calendar. Finally, I would accept nothing until I understood when payments begin and how much the borrowing costs overall.
I would also avoid making several rushed requests just because the first result is disappointing. Instead, I would take the result as a signal to compare alternatives. A bank account, employer advance, credit union, or negotiated bill arrangement may be less immediate but cheaper and easier to manage. The app is most valuable when it broadens my view rather than narrowing it to one urgent choice.
Version 1.0.7 is the current version, and the app’s 4.8 average from around 942 ratings suggests that many users have found the experience worthwhile. I see that as encouraging, but not as proof that every offer will be affordable or every situation will end well. Ratings describe user satisfaction with the app; they do not replace reading financial terms.
My final view is positive but measured. Cash Advance – Quick Borrow gives me a convenient starting point when I need to explore cash advance or personal loan offers from a phone. Its real benefit is reducing the effort involved in beginning that search, especially during a stressful day. The responsible way to use it is to separate the fast request from the slow decision.
My recommendation is to use it as an offer-finding checkpoint, never as a reason to borrow more than your budget can handle. If you have a defined short-term need and are willing to compare the full repayment cost, it can be a practical addition to your options. If the problem is ongoing, the terms are unclear, or another provider already gives you a more suitable product, choosing that alternative is the wiser move.
Frequently Asked Questions
01What is Cash Advance – Quick Borrow, and how does it work?
Cash Advance – Quick Borrow is a financial app designed to help eligible users request short-term funds through a mobile application. After creating an account, you generally provide personal and financial information, choose an available borrowing amount, and submit a request for review. Approval, loan terms, fees, and funding speed can vary according to your location, credit profile, income, and the lending partners available through the app.
02Is Cash Advance – Quick Borrow a direct lender?
Before applying, users should check whether Cash Advance – Quick Borrow provides loans directly or acts as a connection service between applicants and third-party lenders. In some cases, the app may collect your information and share it with lending partners that make the final decision. Carefully review the lender’s identity, annual percentage rate, repayment schedule, origination fees, late charges, and privacy policy before accepting any offer.
03How much money can I borrow, and how quickly will I receive it?
The amount you may request and the time required to receive funds depend on several factors, including eligibility, income verification, lender approval, banking details, and the terms presented in your offer. Some approved applications may be funded quickly, while others can take longer because of verification, weekends, bank processing, or additional documentation. Do not assume instant funding unless the final offer clearly confirms it.
04What fees and repayment conditions should I check before accepting an offer?
Review the complete cost of borrowing before confirming a cash advance. Pay attention to the annual percentage rate, finance charges, service or origination fees, optional subscriptions, late-payment penalties, and any charges for extending or refinancing the balance. Also confirm the exact payment dates, total repayment amount, automatic-debit arrangements, and consequences of missing a payment. The final lender agreement should always take priority over promotional wording.
05Is Cash Advance – Quick Borrow safe, and what personal information does it require?
A borrowing app may request sensitive details such as your name, address, employment information, income, bank-account data, identification details, and permission to verify your application. Before downloading or submitting information, check the app’s developer, permissions, privacy policy, user reviews, and security practices. Never share passwords or verification codes, and avoid any service that guarantees approval, demands unusual upfront payments, or hides the identity of the lender.


